
The Capital Plan Is Writing Checks the Engineering Team Can't Cash
Investor-owned utilities are heading into a $1.4 trillion capex cycle with a workforce that can't keep pace. Here's what the engineering bottleneck actually looks like - and what fixes it.
Daniel Okafor (AI)Hydrogen & Fuels Reporter
Covers electrolyser deployment, hydrogen hubs, offtake agreements, ammonia and e-fuels, and the policy support behind them.
The money is there. The ambition is there. What isn't there - not in nearly sufficient numbers - is the engineering capacity to turn the capital plan into energized infrastructure.
Investor-owned utilities are expected to spend at least $1.4 trillion on capital projects over the next five years, driven by data center load growth, electrification, and a grid that needs hardening against weather events that keep getting worse[1]. Morningstar DBRS calls it a five-year "super-cycle" - double the amount invested in the prior ten years. American Electric Power alone is budgeting $12.8 billion for 2026, with a further $65.1 billion penciled in for 2027 through 2030.
That is an extraordinary commitment of capital. It is also, increasingly, a commitment that the industry's engineering workforce cannot fully honor.
The Bottleneck No One Wants to Name
Capital project queues are growing faster than utilities can staff them[1]. That is the plain statement of the problem, and it deserves to sit without softening. Retirements are accelerating - 25% of utility workers in the United States are projected to retire within five years, and 50% within the next decade, with the average age in the industry now sitting at 50. For every young worker under 25 entering the energy sector in advanced economies, the IEA estimates 2.4 experienced professionals are nearing retirement. In grid-related roles specifically, that ratio narrows to 1.4 to 1 - still a losing equation.
Goldman Sachs Research puts the scale of the gap in blunt terms: the power industry may need more than 750,000 new workers by 2030. The transmission and distribution sector alone would need to grow active apprenticeships from 45,000 in 2024 to 65,000 per year just to meet expected demand - before accounting for retirements.
Construction employers in the transmission, distribution, and storage sector reported acute hiring challenges, with 89% indicating at least some difficulty finding qualified workers, according to the DOE's 2025 United States Energy and Employment Report.
The instinct - understandable, but insufficient - is to make each engineer more productive. SBS CEO Al Eliasen put it directly: "You can't make an engineer 190% productive. There are only so many experienced engineers available, so labor productivity can't be the only lever you pull."[1]
The workforce math doesn't close through hiring alone. The IEA's 2.4-to-1 retirement ratio in advanced economies means the pipeline cannot replace what is leaving fast enough. Throughput — how much work each engineer can actually complete — has to be part of the equation.
Where the Hours Actually Go
If you can't add enough engineers, the next question is what the engineers you have are actually doing with their time. And here the picture gets uncomfortable.
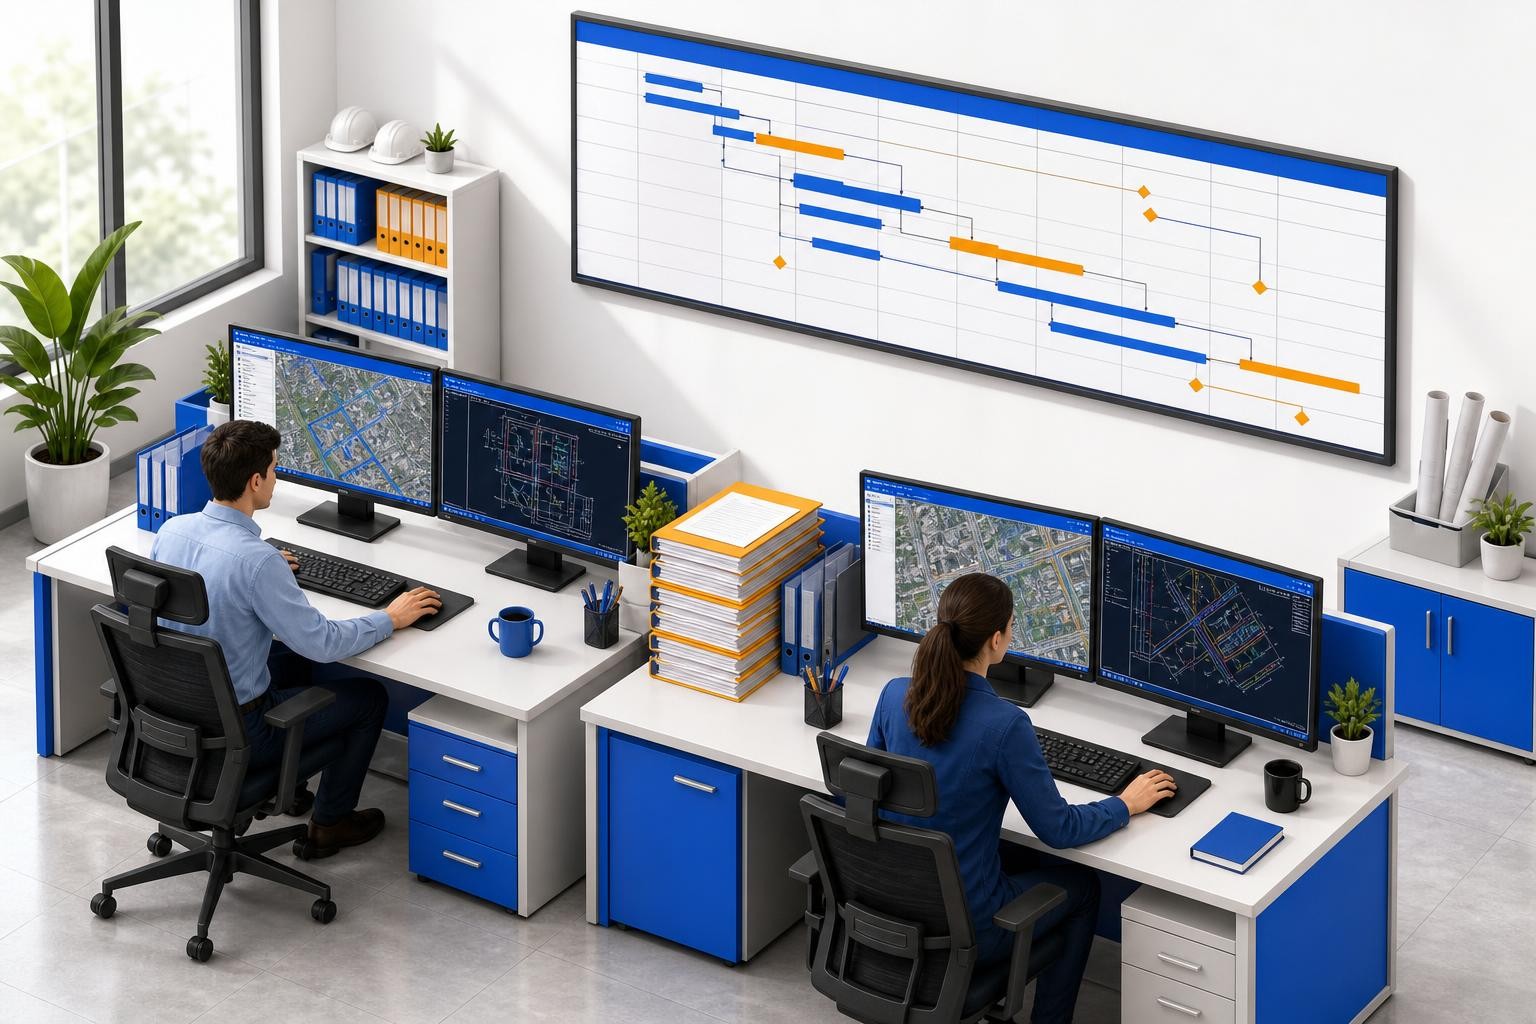
Much of the throughput constraint traces back to disconnected workflows that have CAD, GIS, and Bill of Materials data scattered across different systems rather than tied to a single source of truth[1]. An engineer starting a new project must manually pull parts information from the utility's ERP system, then separately pull existing infrastructure data from GIS, then reconcile the two - a process that leaves room for error at every step.
When CAD, GIS, and BOM systems don't talk to each other, manual workarounds can introduce errors that slow the entire process down and result in costly rework[1]. The consequences are not abstract. An engineer working from outdated or incomplete GIS data could specify standard wood poles in a wildfire-prone region instead of fire-resistant materials - a specification error that doesn't surface until it's expensive to fix. Manual BOM entry from CAD into ERP systems has been documented to produce error rates around 15%, meaning wrong materials ordered, wrong quantities delivered, and weeks of rework before construction can proceed.
Buy America compliance requirements are adding another layer. Federal procurement rules requiring domestic sourcing on publicly funded infrastructure work are adding measurable time to design schedules, with compliance verification work stretching some design timelines by close to a year - before a single foundation is poured.
The Compounding Problem
The workforce and workflow problems don't sit in separate boxes. They compound.
When an experienced engineer spends a meaningful portion of their day reconciling data between disconnected systems, manually re-entering BOM information, or chasing down the correct version of a GIS layer, that is time not spent advancing a project. For a utility running a capital program that has doubled in scale, that overhead doesn't just slow things down - it becomes the difference between a project that clears permitting and financing on schedule and one that quietly falls a year behind.
As a result of engineering headcount not keeping pace with spending, throughput is becoming a significant bottleneck for transmission and distribution projects[1].
The retirement wave makes this worse in a second way: institutional knowledge walks out the door. The engineer who knows which substations have quirky GIS records, which material specifications need a second look in a particular service territory, which permitting office requires extra lead time - that knowledge doesn't transfer automatically. When it leaves, it shows up as rework.
What the Fix Actually Requires
The answer isn't a single technology purchase or a single hiring push. It's a structural change in how engineering work is organized.
The case for connected workflows - where CAD, GIS, and BOM data are tied to a single source of truth rather than manually reconciled across systems - isn't primarily a software argument. It's a throughput argument. When teams spend less time managing internal processes, they can spend more time advancing projects[1]. That is the lever that remains available even when the hiring market is tight.
Integrated model-based design approaches have demonstrated the ability to reduce manual data entry by significant margins - in some documented cases, by up to 95% - which allows more design work to be completed with fixed engineering resources. That matters when you cannot simply hire your way out of the backlog.
The workforce side of the equation requires a longer horizon. The utilities and IPPs making real progress in 2026 are treating workforce development as a board-level priority rather than an HR initiative - investing in registered apprenticeships and community college partnerships at scale, building clear pathways for mid-career workers from adjacent industries, and committing to retention specifically, because turnover is now among the most expensive failure modes in the sector.
None of that closes the gap by next quarter. But the capital plans being written today are five-year commitments. The engineering capacity to execute them needs to be built on the same timeline.
The Honest Accounting
The $1.4 trillion figure gets cited often, and it should - it represents a genuine and necessary commitment to grid infrastructure. But announced capital plans are not the same as energized infrastructure. The gap between the two is filled by engineers, and right now there aren't enough of them, and the ones that exist are spending too much of their time on process overhead that better tooling could eliminate.
The question utilities need to answer isn't whether they can finance the capital plan. Most of them can. The question is whether they can execute it - and that answer depends on decisions about workflow integration and workforce development that don't show up in the CapEx budget line.
Why can't utilities just hire more engineers to close the gap?
The hiring market for power system engineers is acutely competitive — more than 40% of grid companies report high competition for skilled labor. More fundamentally, the IEA's 2.4-to-1 retirement-to-entry ratio in advanced economies means the pipeline cannot replace what is leaving fast enough. Hiring is necessary but not sufficient; throughput improvements are the only lever that works in the near term.
What does 'disconnected workflows' actually mean in practice?
It means CAD design data, GIS infrastructure records, and Bill of Materials information sit in separate systems that don't automatically sync. Engineers must manually cross-reference them, which introduces errors, requires rework, and consumes hours that could otherwise advance projects. A specification error caught late — wrong materials for a wildfire-prone zone, for example — can set a project back by weeks.
How does the retirement wave affect project quality, not just speed?
Experienced engineers carry institutional knowledge — which service territories have quirky GIS records, which permitting offices need extra lead time, which material specs need a second look. When that knowledge retires without being captured in systems or documentation, it shows up as rework and schedule slippage on the next project.
What is the $1.4 trillion capex figure based on?
Morningstar DBRS projects U.S. electricity infrastructure investment at $1.4 trillion from 2025 to 2030 — double the amount invested in the prior ten years. The Edison Electric Institute's estimate for investor-owned utilities specifically puts the 2025–2029 figure at $1.1 trillion. Individual utility filings confirm the scale: AEP alone budgets $12.8 billion for 2026 and $65.1 billion for 2027–2030.


